← News Topics

Bonds: From a Simple Promise to a Powerful Market

Day 3: How Did Home Loans Become Global Investments?

債券:単純な約束から大きな力を持つ市場へ ― 第3日:住宅ローンはどのようにして世界的な投資商品になったのか

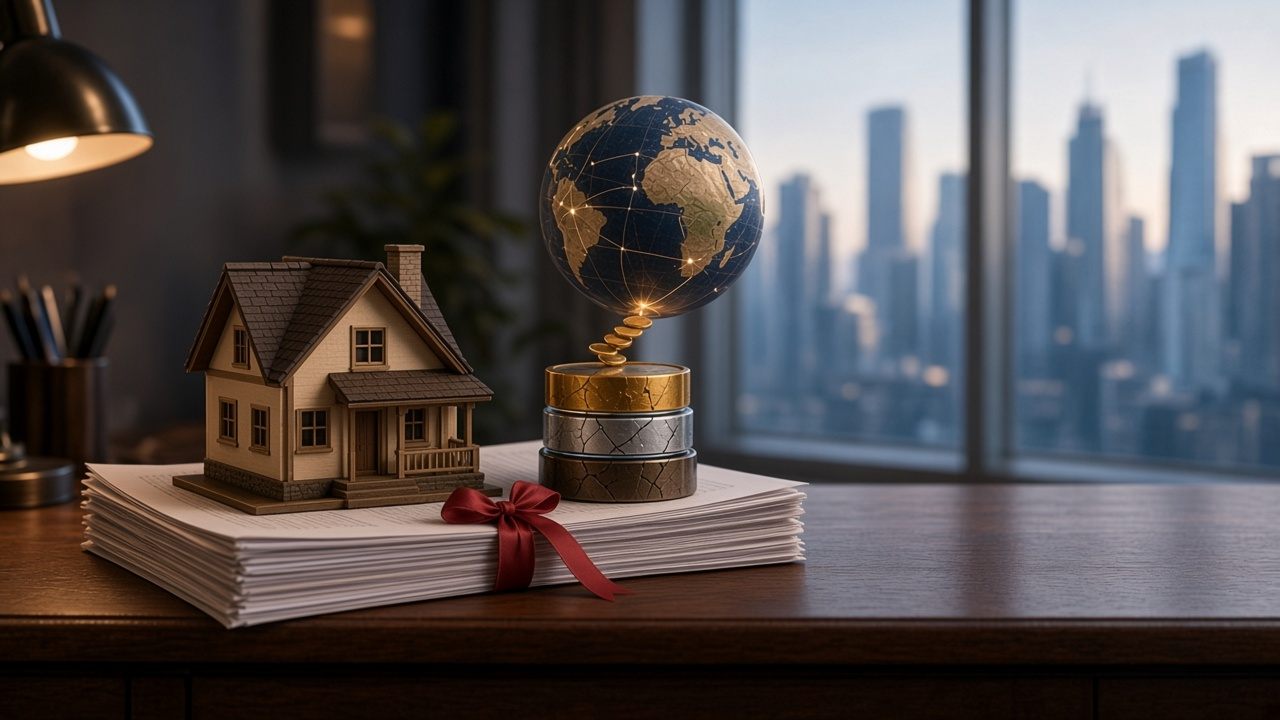
A small model house resting on a stack of loan documents tied with a red ribbon, beside a three-layer gold, silver and cracked bronze stack and a glowing globe on a desk overlooking a city skyline

Imagine that a family borrows $300,000 from a bank to buy a house. This loan is called a mortgage. The bank provides the money, and the family repays it each month. Traditionally, the bank would keep the loan for many years. In modern finance, however, it can sell the loan—and the right to collect its future payments—to another financial institution.

ある家族が、家を買うために銀行から30万ドルを借りると想像してください。このローンは住宅ローン(モーゲージ)と呼ばれます。銀行がお金を出し、家族は毎月それを返済します。従来、銀行はそのローンを何年も手元に持ち続けていました。しかし現代の金融では、銀行はそのローンを、将来の返済金を受け取る権利とともに、別の金融機関に売ることができます。

That institution buys thousands of mortgages and places them together in a bundle. It then creates a financial product supported by the payments from all those mortgages. This process is called securitization, and the product is known as a mortgage-backed security. Investors who buy it are not buying the houses themselves. They are buying the right to receive a share of the homeowners’ monthly payments. These payments create a cash flow for the investors. The original lenders receive money from the sale and can use it to make new loans. However, this system also separates the lender that approves the mortgage from the investor who may eventually bear the loss.

その金融機関は何千もの住宅ローンを買い取り、それらを一つの束にまとめます。そして、それらすべての住宅ローンからの返済金に裏付けられた金融商品を作ります。この過程は証券化と呼ばれ、その商品は住宅ローン担保証券(MBS)として知られています。それを買う投資家は、家そのものを買っているわけではありません。住宅所有者が毎月支払う返済金の一部を受け取る権利を買っているのです。これらの返済金が、投資家にとってのキャッシュフローを生み出します。もともとの貸し手は売却によってお金を受け取り、それを新しい融資に使うことができます。しかしこの仕組みは、住宅ローンを承認する貸し手と、最終的に損失を負うかもしれない投資家とを切り離すことにもなります。

A mortgage-backed security can be divided into sections called tranches. When homeowners make their monthly payments, investors in the highest tranche are paid first. Investors in the lower tranches are paid later. If some homeowners stop repaying their mortgages, the lower tranches absorb the losses first. Their investors may receive less income or may not recover all the money they invested. Because these tranches carry a greater risk of loss, they usually offer higher possible returns. Rating agencies give each tranche a credit rating to show how likely its investors are to receive the promised payments. However, if the rating is based on overly optimistic assumptions, a tranche containing risky mortgages can appear safer than it really is.

住宅ローン担保証券は、トランシェと呼ばれる区分に分けることができます。住宅所有者が毎月の返済をすると、最上位のトランシェの投資家が最初に支払いを受けます。下位のトランシェの投資家は、その後に支払いを受けます。一部の住宅所有者がローンの返済をやめると、下位のトランシェが最初に損失を吸収します。その投資家たちは、受け取る収入が減ったり、投資したお金を全額は取り戻せなかったりするかもしれません。こうしたトランシェは損失のリスクが大きいため、通常はより高い収益の可能性を提供します。格付け機関は、各トランシェの投資家が約束された支払いを受け取れる可能性がどれくらいかを示すため、それぞれに信用格付けを与えます。しかし、その格付けが楽観的すぎる前提に基づいていれば、リスクの高い住宅ローンを含むトランシェが、実際よりも安全に見えてしまうことがあります。

Before the 2008 financial crisis, many U.S. lenders made subprime mortgages to borrowers with weak credit histories. Some of these loans began with low monthly payments that later increased. While house prices were rising, borrowers who could no longer afford their payments often had an escape route: they could refinance the mortgage or sell the house for enough money to repay the loan. When house prices fell, that escape route disappeared. Some homes became worth less than the amount still owed, and lenders became less willing to offer new loans. As monthly payments increased, more borrowers fell behind and entered foreclosure. The cash flowing into mortgage-backed securities weakened, and their prices collapsed. Because financial institutions around the world owned these products, losses that began with American home loans spread through the global system.

2008年の金融危機の前、多くのアメリカの貸し手は、信用履歴の弱い借り手にサブプライム住宅ローンを提供していました。こうしたローンの中には、最初は毎月の返済額が低く、後で上がるものもありました。住宅価格が上がっている間は、返済を続けられなくなった借り手にも、たいてい逃げ道がありました。ローンを借り換えるか、ローンを返済できるだけの金額で家を売ることができたのです。住宅価格が下がると、その逃げ道はなくなりました。一部の家は、まだ残っている借金の額よりも価値が低くなり、貸し手は新しい融資に消極的になりました。毎月の返済額が増えるにつれ、返済が滞る借り手が増え、差し押さえに至りました。住宅ローン担保証券に流れ込むお金は細り、その価格は暴落しました。世界中の金融機関がこれらの商品を保有していたため、アメリカの住宅ローンから始まった損失は、世界の金融システム全体に広がりました。

Securitization is not necessarily harmful. It can provide lenders with more funding and spread risk among many investors. The danger appears when lending standards become weak, financial products become too complex, and investors trust ratings without understanding the loans underneath. The crisis revealed a basic truth: financial engineering can move risk, divide it, and hide it—but it cannot make risk disappear.

証券化は、必ずしも有害なものではありません。貸し手により多くの資金をもたらし、リスクを多くの投資家に分散させることができます。危険が生じるのは、融資の基準が甘くなり、金融商品が複雑になりすぎ、投資家がその裏にあるローンを理解しないまま格付けを信頼するときです。この危機は、一つの基本的な真実を明らかにしました。金融工学はリスクを移し、分け、隠すことはできますが、リスクを消し去ることはできないのです。
Vocabulary

  1. mortgage — a loan used to buy a house or other property. Example: The family took out a mortgage to buy its first home.
  2. bundle — a group of things collected and treated as one unit. Example: The institution created a bundle of home loans.
  3. securitization — the process of turning loans or other financial claims into securities that can be sold to investors. Example: Securitization connects individual borrowers with large financial markets.
  4. mortgage-backed security — a financial product supported by payments from a group of mortgages. Example: The investment fund bought a mortgage-backed security.
  5. cash flow — money moving into or out of a business or investment. Example: Homeowners’ monthly payments create cash flow for investors.
  6. tranche — one section of a financial product with a particular level of risk and return. Example: The lower tranche absorbs losses before the higher one.
  7. credit rating — an assessment of how likely a borrower or financial product is to make its promised payments. Example: The tranche received a high credit rating.
  8. subprime — describing a loan made to a borrower with a relatively weak credit history. Example: Many subprime mortgages carried a high level of risk.
  9. foreclosure — the legal process through which a lender takes a property after the borrower fails to make payments. Example: The family faced foreclosure after missing several payments.

Comprehension Questions

  1. What do investors in a mortgage-backed security buy?
    1. Ownership of the houses
    2. The right to receive a share of homeowners’ payments
    3. The right to set mortgage interest rates
    4. Ownership of the original bank

    住宅ローン担保証券の投資家は、何を買っているのですか?

  2. Why might a lender sell its mortgages?
    1. To receive money sooner and make more loans
    2. To stop borrowers from buying houses
    3. To remove all risk from the financial system
    4. To increase the value of every house

    貸し手が住宅ローンを売ることがあるのはなぜですか?

  3. What happens if some homeowners stop making payments?
    1. Investors in the highest tranche always lose money first.
    2. Every investor immediately loses the same amount.
    3. Investors in the lower tranches absorb losses first.
    4. The original mortgages automatically disappear.

    一部の住宅所有者が返済をやめると、何が起こりますか?

  4. Why did falling house prices create problems for some borrowers?
    1. Their monthly payments automatically became zero.
    2. They could no longer easily refinance or sell their homes to repay the loans.
    3. Banks stopped accepting all monthly payments.
    4. Their credit ratings immediately improved.

    住宅価格の下落が、一部の借り手に問題を引き起こしたのはなぜですか?

  5. What basic lesson did the financial crisis reveal?
    1. Risk disappears when it is divided.
    2. Credit ratings are always accurate.
    3. Securitization should never be used.
    4. Financial engineering can hide risk but cannot eliminate it.

    金融危機は、どのような基本的な教訓を明らかにしましたか?

Discussion Questions

  1. Why might separating the original lender from the final investor weaken lending standards?

    もともとの貸し手と最終的な投資家を切り離すことで、融資の基準が甘くなることがあるのはなぜでしょうか?

  2. What are the possible benefits of combining many mortgages into one financial product?

    多くの住宅ローンを一つの金融商品にまとめることには、どのような利点がありうるでしょうか?

  3. Why might investors depend too heavily on credit ratings?

    投資家が信用格付けに頼りすぎてしまうことがあるのはなぜでしょうか?

  4. How did problems involving individual American home loans become a global financial crisis?

    アメリカの個々の住宅ローンをめぐる問題は、どのようにして世界的な金融危機になったのでしょうか?

  5. Should financial products be limited when they become too difficult for investors to understand?

    金融商品が投資家にとって理解しにくくなりすぎた場合、それを制限すべきでしょうか?

Speaking Task

Explain how a home loan can become a global investment.

住宅ローンがどのようにして世界的な投資商品になりうるのかを説明してください。

Include:

  • how a mortgage begins

    住宅ローンがどのように始まるか

  • how mortgages are bundled and sold

    住宅ローンがどのように束ねられ、売られるか

  • how tranches divide payments and losses

    トランシェが返済金と損失をどのように分けるか

  • why problems in the U.S. housing market spread through the global financial system

    アメリカの住宅市場の問題が、なぜ世界の金融システムに広がったのか

Speak for about one minute.

約1分間話してください。